What the online application gives you
Three practical ways to move forward, whether you prefer to talk it through or simply send the paperwork.
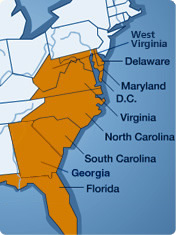
Choice Finance is a mortgage lending company serving homeowners and buyers across Maryland, Virginia, Washington D.C., and Delaware. The organization pairs a national online lending platform with local branch offices, allowing borrowers to start an application online and be matched with a dedicated Loan Officer who understands the regional housing market. This combination of digital convenience and in-person guidance shapes the way many borrowers first encounter the company and the way their files are handled from pre-approval through closing.
The application process begins with a secure preliminary online form that captures basic financial and property information. Once submitted, the file is routed to a Loan Officer covering the borrower's area, who reviews the details and outlines available programs. Applicants can also request information by phone, email, live chat, or by mail, and a blank loan form can be provided by mail or fax for those who prefer a traditional paper approach to starting a home or commercial loan.
Choice Finance offers a broad menu of home loan programs, including conventional fixed-rate mortgages, adjustable-rate mortgages, FHA loans, and jumbo financing for larger loan amounts. Borrowers shopping for a refinance can compare refinance options and payment scenarios using the site's calculators, while those considering a purchase can explore rate options and gauge how a proposed loan might affect their monthly budget before committing to a full application.
Mortgage calculators and educational resources are positioned as practical tools rather than marketing content. A payment calculator, rate comparison features, and general home finance articles help borrowers estimate monthly payments, understand closing costs, and think through the tradeoffs between fixed and adjustable structures. These resources are useful for shoppers who want a clearer sense of affordability before contacting a Loan Officer or submitting a pre-approval request.
Local market knowledge is central to how the company describes its service. Loan Officers work within the communities they serve, familiar with regional pricing, common home types, and the rhythms of local real estate activity. This market familiarity is presented as an advantage over purely online lenders, since a local officer can answer questions in context, anticipate friction points during underwriting, and keep borrowers informed as a file progresses toward closing.
Borrowers receive a pre-approval letter that can strengthen an offer when working with a real estate agent. With pre-approval in hand, sellers and agents can see that a buyer has been vetted on credit, income, and asset qualification, which can help differentiate offers in competitive markets. The company frames this step as part of a broader effort to help clients move from searching for homes to submitting a well-prepared application with a realistic chance of approval.
The company highlights a long history of serving clients and working with real estate professionals across its footprint, including ties to the Washington D.C. metropolitan area. Testimonials and written client feedback are featured as evidence of the service experience, while the emphasis remains on communication: keeping borrowers updated, answering questions promptly, and explaining each stage of the process so that clients understand what is happening with their loan and what happens next.
Refinancing is treated as a distinct journey from purchasing, with its own set of options and considerations. Existing borrowers may explore whether a new rate structure would improve their payment, whether fees associated with a refinance are justified, or whether they simply want to adjust the term of their loan. Rate options are shared and compared side by side so borrowers can weigh the cost tradeoffs and decide whether refinancing makes sense for their household at the moment.
Commercial loans sit alongside home financing in the company's product offering, extending the same local-network approach to business borrowers. A Loan Officer can review a commercial request, discuss the structure of the financing, and guide the applicant through documentation and underwriting. The result is a single point of contact for both personal and business mortgage needs, supported by calculators, educational content, and application tools designed to make the process easier to begin.